
BOJ Basel III Capital Adequacy Framework
A three-day workshop for financial officers in the Jamaican banking industry on regulatory capital, risk-weighted assets, capital planning and supervisory readiness.
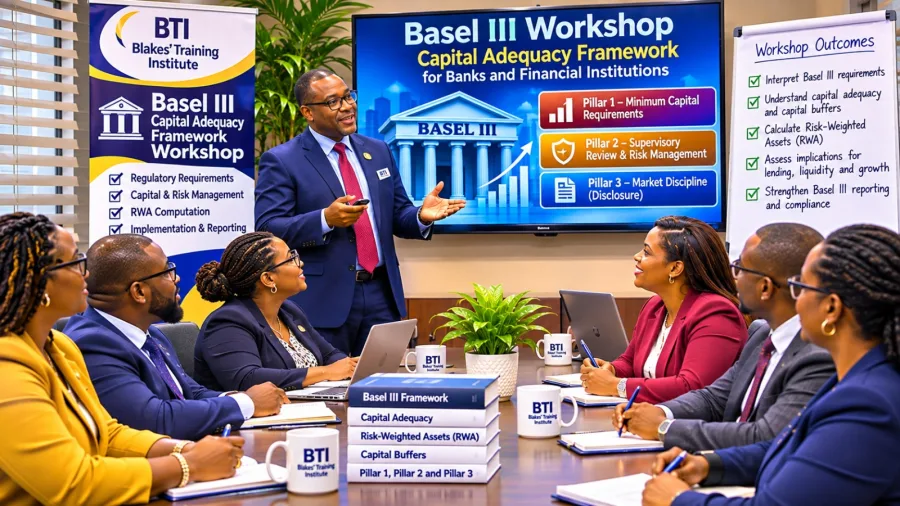
What this programme addresses
The Basel III Capital Adequacy Framework represents a significant development in prudential regulation and financial institution management. It is designed to strengthen the quality and quantity of capital financial institutions maintain, improve risk measurement and management, increase resilience to financial and economic shocks, and strengthen market confidence. For Jamaican financial institutions, understanding how Basel III principles interact with the Bank of Jamaica’s prudential supervisory framework is essential for finance, risk, treasury, credit, compliance, audit and senior-management professionals.
This three-day workshop provides participants with a practical understanding of the BOJ Basel III Capital Adequacy Framework, including regulatory capital, risk-weighted assets, capital ratios, credit risk, market risk, operational risk, capital buffers, leverage, liquidity considerations, supervisory review and disclosure. The programme will also examine how capital adequacy connects with governance, strategic planning, lending, portfolio management and the wider Jamaican regulatory environment. Participants will work through practical exercises, calculations, scenarios and case studies that connect Basel III requirements to risk management, financial resilience and sustainable banking strategy.
Workshop objectives
- Explain the Basel III framework and its relevance to Jamaica. Understand the purpose, evolution and structure of Basel III and how its principles support the safety, soundness and resilience of financial institutions.
- Understand the components and quality of regulatory capital. Distinguish among Common Equity Tier 1 (CET1), Additional Tier 1 and Tier 2 capital, and understand deductions, adjustments and the importance of loss-absorbing capital.
- Calculate and interpret key capital-adequacy measures. Understand the relationship among regulatory capital, risk-weighted assets (RWA) and capital ratios, and assess how changes in assets, lending, risk weights, profitability and capital affect an institution’s capital position.
- Understand how major banking risks affect capital requirements. Examine the relationship between capital adequacy and credit risk, market risk and operational risk, together with the importance of risk measurement, controls and portfolio management.
- Apply Basel III principles to governance, planning and decision-making. Understand how capital adequacy affects lending growth, dividends, strategic planning, pricing, portfolio composition, stress testing, risk appetite, capital planning and management decisions.
- Strengthen regulatory compliance and supervisory readiness. Understand the respective roles of BOJ and other relevant Jamaican regulatory and financial-sector bodies, strengthen regulatory reporting and governance, and improve the institution’s preparedness for supervisory review.
Recommended participants
- Chief Financial Officers and finance managers
- Financial controllers and senior accounting personnel
- Treasury managers and treasury officers
- Chief Risk Officers and enterprise-risk professionals
- Credit risk managers and credit analysts
- Credit officers and lending managers
- Corporate, commercial, SME and retail lending managers
- Asset and Liability Management personnel
- ALCO members
- Capital-management and balance-sheet-management professionals
- Compliance officers
- Regulatory reporting officers
- Internal auditors and audit managers
- Operational-risk managers
- Market-risk professionals
- Financial analysts
- Strategic planning professionals
- Branch and operations managers requiring greater prudential-risk knowledge
- Senior managers and executives
- Board and board-risk/audit committee members requiring an executive understanding of Basel III
Best suited for
The programme can also be adapted for banks, building societies, financial holding companies and other relevant BOJ-supervised institutions, depending on the institution’s regulatory status and applicable requirements.
Key topics
- Day 1 — Basel III and Regulatory Capital
- Basel III principles and the Jamaican prudential supervisory context
- CET1, Additional Tier 1 and Tier 2 capital
- Deductions, adjustments, loss absorption and capital buffers
- Leverage and liquidity considerations
- Day 2 — Risk-Weighted Assets and Capital Ratios
- Credit, market and operational risk
- Risk weights, portfolio composition and risk controls
- Practical RWA and capital ratio calculations
- Scenarios on changes in lending, profitability and capital
- Day 3 — Capital Planning, Governance and Supervisory Readiness
- Capital planning, risk appetite and stress testing
- Implications for lending growth, pricing, dividends and strategy
- Regulatory reporting, supervisory review and disclosure
- Case study on capital decisions and supervisory readiness